Cash Offer Negotiation: Closing the Deal
Cash Offer Negotiation: Closing the Deal
Cash home offers for Sterling and Northern Virginia homeowners start with a property evaluation, followed by a firm all-cash proposal delivered without financing contingencies. Sellers review terms directly with the buyer, ask questions, and accept on their own timeline. Closing typically happens in about two weeks, compared to the standard 30–60 days required for mortgage-backed sales.
Key Takeaways
- Cash offers now represent a significant and growing share of all home sales nationwide.
- Cash sales close faster than financed purchases because buyers already have funds available without lender delays.
- Sellers often accept below-asking prices for all-cash offers due to the certainty and speed of closing.
- Direct buyer-to-seller transactions eliminate financing requirements, reducing steps and simplifying the entire negotiation process.
What Is a Cash Offer, and Why Consider It?
A cash offer means the buyer pays the full sale price upfront, with no mortgage lender involved anywhere in the transaction. For a Sterling homeowner, that detail changes everything about how a sale moves forward. No loan means no underwriting delays, no appraisal contingency tied to financing, and no risk of a deal collapsing weeks before closing because a bank said no.
Cash sales have moved from a rare option to a common one. Cash offers now represent a substantial and growing share of home sales nationwide. That shift matters for Northern Virginia sellers weighing speed against the traditional listing process.
WeBuyNOVA purchases houses for cash, as-is, with no repairs, no realtor commissions, and no hidden fees. That structure keeps cash offer negotiation simple: the number presented reflects what the seller actually receives, not a figure reduced later by closing costs or commission splits.
Why does skipping a mortgage lender matter to a seller?
Removing the lender removes the biggest source of delay and uncertainty in a home sale. Financed deals can fall through over appraisal gaps, loan denials, or last-minute underwriting conditions. A cash sale sidesteps those risks entirely, giving sellers a clearer path to a firm closing date.
Offer negotiation tips for sellers often start here:
- Confirm proof of funds and verify its legitimacy before discussing price.
- Ask what "as-is" covers in the written offer, clarifying repairs versus price concessions.
- Understand which fees, if any, come out of the final number to avoid surprises.
- Evaluate the earnest money deposit as part of the offer to assess buyer commitment.
- Negotiate realistic and clear closing timelines that align with your needs.
Sellers who avoid realtor commissions and hidden fees see transparent pricing, with the offered amount matching the amount paid at closing.
How Do Cash Buyers Calculate Your Offer?
Three primary factors drive most cash offer numbers: the home's current condition, needed repairs, and local market conditions. Cash buyers purchase properties in any state. A cracked foundation or an outdated kitchen never removes a homeowner from consideration. That flexibility, though, directly shapes the math behind the number a Sterling homeowner eventually sees.
Repairs top the list. A buyer walks through the property, tallies what it would cost to bring the home to move-in condition, and subtracts a reasonable estimate from the top-line value. Market conditions matter just as much. A neighborhood with rising comparable sales supports a stronger offer than one with stagnant or falling prices. The property's overall condition — roof age, HVAC health, structural soundness — rounds out the calculation.
What information do sellers need to provide upfront?
The process typically starts with basic property details: address, square footage, condition notes, and reason for selling. Buyers use these details to generate a preliminary number, often within 24 hours of submission. Nothing more complicated than a short form is usually required to get that first estimate moving.
How can homeowners tell if an offer is fair?
Fair market value is the benchmark. Before accepting anything, a homeowner should understand what comparable homes in the area have actually sold for recently. Without that baseline, cash offer negotiation becomes guesswork instead of an informed conversation.
Understanding these inputs is the foundation for negotiating with cash buyer offers confidently.
How Does Cash Offer Negotiation Actually Work?
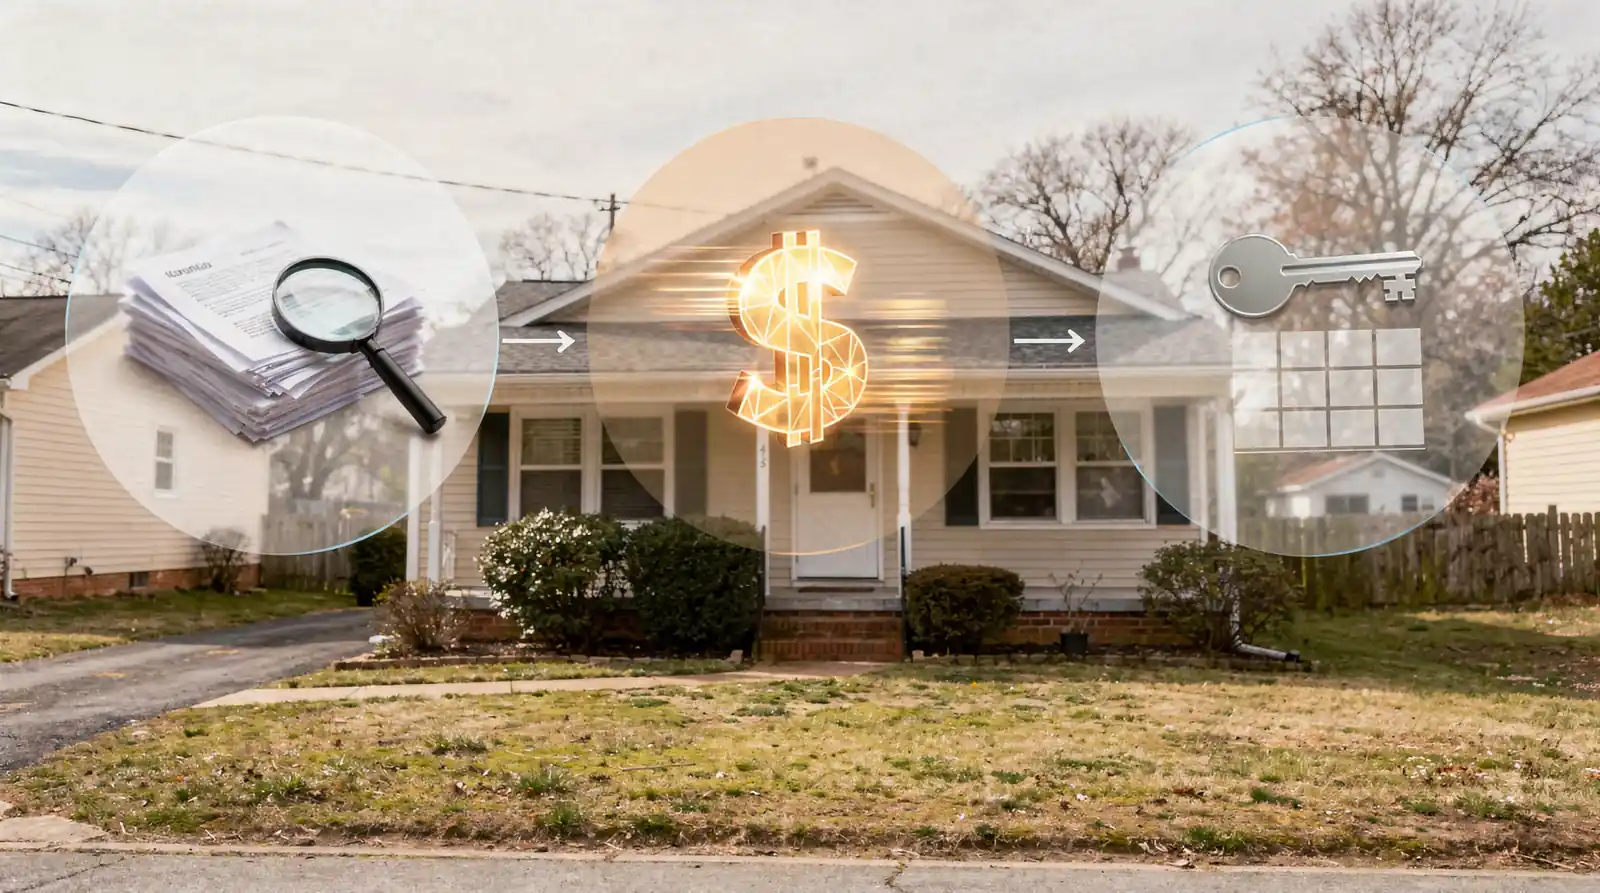
A cash purchase moves through a compressed set of steps: property review, offer, and closing, each happening far faster than a financed sale. Cash offer negotiation starts the moment a buyer reviews the property. Typically produces a written number within 24 to 48 hours. From there, closing often happens within about a week, a pace that leaves little room for the drawn-out back-and-forth common in traditional sales.
Homeowners in Sterling and neighboring communities benefit most when they understand the tradeoffs baked into this speed. Because a cash purchase isn't tied to lender approval, the transaction avoids appraisal delays, underwriting conditions, and financing contingencies that can stall a deal for weeks. That certainty is precisely what negotiating with cash buyer discussions center on: sellers weigh a faster, guaranteed close against the highest possible sale price.
Why would a seller accept less than asking price?
Sellers sometimes accept a lower number specifically because the deal isn't tied to mortgage financing. A transaction free of lender requirements typically closes faster, which removes the risk of a buyer's loan falling through weeks into the process.
How long does the whole process take from offer to close?
Timelines vary, but cash sales commonly close in about two weeks. Far faster than the 30 to 60 days a financed sale usually requires. Some cash buyers deliver an offer within 24 hours and finalize closing in as little as 7 days.
Key offer negotiation tips for sellers weighing a cash deal include:
- Compare the net proceeds of a cash offer against a financed offer minus repair costs and carrying time.
- Confirm proof of funds before finalizing cash offer terms.
- Request clarity on earnest money deposits and their refundable status.
- Negotiate clear, written closing dates rather than estimates.
- Discuss whether repair credits or price reductions better protect your interests.
What Negotiation Tips Help You Get Fair Terms?
Fair terms come from preparation, not luck. Sellers who understand their home's value and ensure a buyer's proof of funds walk into cash offer negotiation with a real advantage instead of guesswork.
Knowing a property's true market worth is the foundation of any solid negotiation strategy. Sellers who skip this step risk accepting less than fair market value, especially since some cash buyers look for a discounted deal. Establishing that baseline first turns negotiating with cash buyer conversations into an informed exchange rather than a one-sided offer.
How can a seller confirm a cash buyer is legitimate?
Legitimacy hinges on documentation, not promises. A serious buyer should be able to produce one of the following before terms get finalized:
- Original or online bank statements showing sufficient funds.
- A line of credit approval notice.
- Certified financial statements.
- A proof of funds letter confirming the cash is readily available.
An offer carries little weight until the buyer proves the full purchase amount actually exists.
Effective offer negotiation tips that move the needle include:
- Request proof of funds documentation early in the conversation.
- Compare the offer against recent local sales to gauge fairness.
- Avoid rushing into agreements before full verification.
- Decide on repair credits vs price reductions with your financial advisor or realtor.
- Negotiate closing timelines that minimize your carrying costs while allowing necessary flexibility.
- Ensure all agreement terms, especially regarding repairs and closing dates, are documented clearly in writing.
Finalizing cash offer terms works best as a step-by-step process, not a single conversation. First, confirm funding. Second, compare the number against the home's documented value. Third, put agreed terms in writing before moving toward closing. In a competitive Sterling-area market, an all-cash offer already stands out from financed buyers, but fair terms still depend on the seller staying informed at every stage.
Steps to Smoothly Finalize Your Cash Offer
- Confirm the buyer’s proof of funds and earnest money deposit details.
- Review and negotiate repairs — decide between accepting repair credits or a price reduction.
- Agree on a clear, written closing timeline that suits your schedule.
- Ensure the purchase terms, including fees and contingencies (or lack thereof), are documented.
- Coordinate with the buyer to prepare closing documents and title work.
- Select and approve the final closing date.
- Complete the transaction with funds transfer and official sale recording.
How Is a Finalized Cash Offer Closed?
A finalized cash sale closes once the buyer handles every paperwork detail and coordinates the timeline directly with the seller. No lender, no appraisal contingency, no waiting on loan underwriting. This structure is what makes finalizing a cash offer faster than a traditional mortgage-backed sale for Sterling-area homeowners.
The steps that carry an offer from acceptance to closing table typically follow this pattern:
- Seller accepts the offer after any cash offer negotiation concludes.
- Buyer prepares closing documents and title work.
- Seller selects a closing date that fits their schedule.
- Closing costs get covered as part of the purchase terms.
- Funds transfer and the sale records.
Sellers dealing with pre-foreclosure or active foreclosure benefit from this same closing structure. A cash buyer able to move quickly through paperwork can finalize a purchase before a foreclosure date arrives, helping protect the homeowner's credit standing in the process.
What Makes a Cash Closing Different From a Financed One?
A financed closing depends on a third-party lender approving the loan, ordering an appraisal, and clearing conditions before funding. A cash closing removes that dependency entirely. Because no mortgage underwriter sits between the offer, the deed transfer, and the timeline shrinks considerably while the seller keeps more control over the closing date.
Who Manages the Details After the Offer Is Accepted?
The buyer typically manages title work, document preparation, and coordination with the closing entity. Sellers focused on negotiating with a cash buyer beforehand can enter this stage with fewer surprises. The terms were already settled.
Homeowners across Northern Virginia, including those working with a Sterling, VA-based buyer, can apply these same offer negotiation tips to keep the closing process smooth from acceptance to final signature. Contact WeBuyNOVA
Checklist for Sellers Engaging in Cash Offer Negotiation
- Verify buyer's proof of funds and earnest money deposit.
- Understand your home's current market value through comps.
- Clarify "as-is" terms and repair responsibilities upfront.
- Negotiate closing timeline to fit your schedule and minimize expenses.
- Review all fees and ensure no hidden costs are deducted from the offer.
- Get all agreed-upon terms and dates in writing before proceeding.
- Confirm who handles closing paperwork and title work.
- Prepare for a smooth and timely closing without lender contingencies.
FAQ
How long does a cash home sale take to close?
Cash sales close in about two weeks, compared to the standard 30–60 days required for mortgage-backed sales, since no lender delays exist.
Why do sellers sometimes accept below-asking offers for cash?
Sellers accept below-asking prices for the certainty and speed all-cash offers provide, avoiding financing contingencies, appraisal gaps, and loan denials common in traditional sales.
What factors determine a cash home offer amount?
Cash buyers calculate offers based on the home's current condition, needed repairs, and local market conditions, including comparable sales and structural elements like roof and HVAC health.
What should a seller look for when evaluating earnest money deposits?
Assess the deposit amount and whether it's refundable. A substantial earnest money deposit signals buyer seriousness and protects the seller in case of default.
How can a seller handle repair credits vs price reductions when negotiating?
Decide which option better suits your financial and tax situation. Repair credits may simplify closing, while price reductions reduce sale proceeds but affect taxable income.
How can sellers close smoothly without contingencies?
By ensuring clear communication, verifying funds early, agreeing on "as-is" terms, and setting firm, written timelines, sellers can close quickly without financing or appraisal contingencies complicating the process.
Conclusion
In closing, negotiating and finalizing a cash home offer represents a straightforward path forward when you understand each stage of the process. From the initial offer through inspection and closing, clarity and direct communication eliminate confusion and accelerate your timeline. By recognizing how cash transactions differ from traditional financing, you position yourself to make informed decisions that align with your specific situation. The simplicity of this approach—removing contingencies, appraisals, and extended timelines—transforms what many experience as a stressful process into a manageable, transparent journey toward resolution.
About the Author
Eunice Johnson is a real estate expert with over a decade of experience in the Sterling, VA housing market. She specializes in helping homeowners navigate the complexities of selling their homes quickly and efficiently, particularly through cash sales.
As a cash home buyer at WeBuyNOVA, Eunice works with motivated home sellers throughout Northern Virginia to build realistic plans and navigate local market conditions. Her deep knowledge of local market trends, grounded in years of hands-on real estate practice, informs the transparent, data-driven advice she offers every seller. That practical expertise and her commitment to clear communication make her a trusted resource for homeowners looking to sell with confidence.
Contact
- 📞 Phone: +1 (571) 200-2365
- ✉️ Email: [email protected]
- 📅 Consultation: Get a Cash Offer
- 🌐 Website: webuynova.com
Serving Sterling, VA and surrounding areas.